
Introduction
International business relationships depend on reliable financial transactions.
A company may buy products from overseas suppliers, pay international service providers, collect invoices from global customers, or settle transactions with distributors in different markets.
These activities require effective b2b cross border payments.
Unlike many consumer transactions, B2B payments often involve larger values, detailed invoices, multiple approval stages, and stricter financial record requirements.
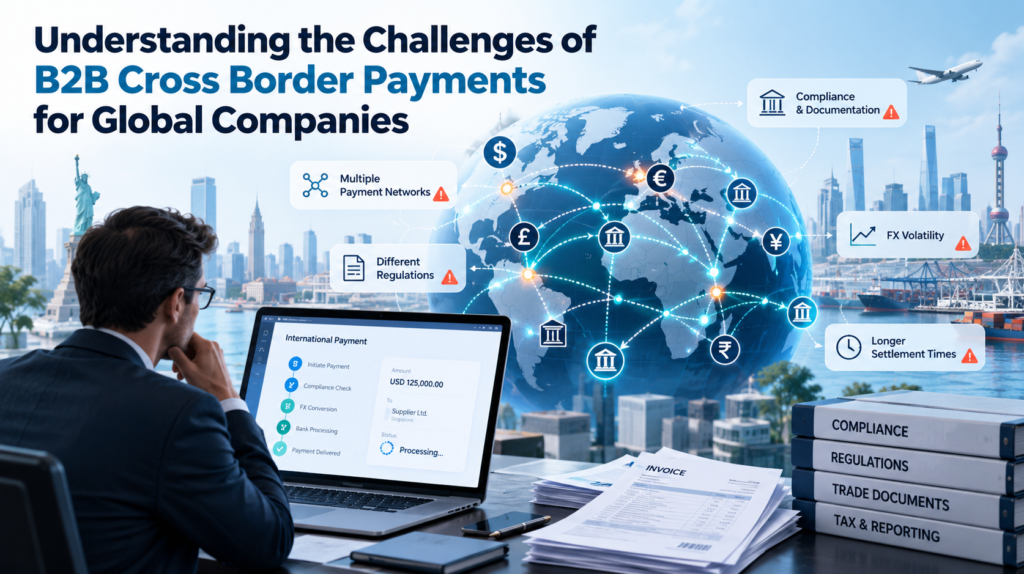
This creates several operational challenges.
Businesses need systems that can handle international transactions efficiently while maintaining accurate records and sufficient financial visibility.
A reliable business payment solution can help companies address many of these challenges.
Challenge 1: Different Currencies
Global companies often work with several currencies.
A supplier may invoice in one currency while the buyer operates primarily in another.
Businesses need to understand the total financial impact of currency conversion.
They should monitor:
- Invoice currency
- Payment currency
- Settlement currency
- Conversion rates
- Transaction charges
Poor currency visibility can make international costs difficult to predict.
Businesses should therefore use payment infrastructure that provides clear transaction information.
Challenge 2: Settlement Delays
International transactions may take longer to settle than domestic payments.
Delays can affect both buyers and suppliers.
A supplier waiting for payment may face its own cash flow challenges.
The buyer may also spend time responding to questions about transaction status.
Reliable cross border payments should provide businesses with sufficient visibility into settlement progress.
Accurate tracking can reduce uncertainty and improve communication between commercial partners.
Challenge 3: Complex Reconciliation
B2B transactions often involve invoices, purchase orders, customer accounts, and internal approval systems.
Finance teams must match each payment with the correct financial record.
This becomes more difficult when payments move across different countries and platforms.
Modern payment solutions can simplify reconciliation by providing structured transaction data.
Businesses can use accurate payment records to match transactions more efficiently.
Automation can further reduce manual work.
Challenge 4: Multiple Payment Systems
Global companies may use different payment systems for different markets.
Over time, this creates fragmented financial operations.
Teams may need to switch between several platforms to:
- Check payment status
- Download reports
- Track settlements
- Reconcile transactions
- Review international payments
A centralized business payment solution can reduce this complexity.
Bringing transaction information together makes global payment management easier.
Challenge 5: Compliance Requirements
International financial transactions may be subject to different regulatory requirements.
Companies need to understand the rules that apply to their markets and transaction types.
Compliance considerations may relate to:
- Identity verification
- Financial reporting
- Transaction monitoring
- Data protection
- Record keeping
Businesses should evaluate payment providers carefully and ensure that their payment processes align with applicable requirements.
Challenge 6: Payment Security
Higher-value B2B transactions require strong security.
Unauthorized transactions can create significant financial losses.
Businesses need appropriate controls for payment authorization and account access.
Security measures may include:
- User authentication
- Access permissions
- Transaction monitoring
- Approval workflows
- Secure data handling
Strong security helps protect business finances and maintain trust between international partners.
Challenge 7: Limited Transaction Visibility
Finance teams need to know where money is at each stage of the payment process.
Poor visibility creates uncertainty.
A payment platform should provide clear information about:
- Payment initiation
- Transaction status
- Settlement
- Currency
- Fees
- Recipient information
Better visibility makes financial planning easier.
The Role of Online Payment Solutions
Although B2B transactions may differ from consumer payments, online payment solutions can still support digital business transactions.
Companies increasingly use digital platforms to issue invoices, collect payments, and manage financial interactions.
Online payment infrastructure can reduce reliance on manual processes and improve transaction speed.
It can also provide more convenient ways for business customers to make payments.
Pay-in Services for B2B Collections
Global companies also need effective ways to receive money from business customers.
Pay-in services can help companies manage incoming transactions.
They may support:
- Customer collections
- Invoice payments
- Transaction tracking
- Reconciliation
- Financial reporting
Reliable Pay-in services can improve cash flow visibility and make international collections more organized.
Improving Supplier Relationships
Payment performance affects supplier relationships.
Suppliers value predictable and transparent payment processes.
If transactions are regularly delayed or difficult to track, commercial trust may decline.
Efficient business payments help companies maintain better relationships with international suppliers.
Clear transaction records also reduce the number of payment-related disputes.
Automation Can Reduce Complexity
Automation can make B2B payment operations more efficient.
Businesses can automate:
- Payment records
- Approval workflows
- Reconciliation
- Payment notifications
- Settlement tracking
- Reporting
This becomes increasingly important as transaction volumes grow.
Automation allows finance teams to focus more on planning and less on repetitive administrative work.
How Uniteller Can Be Evaluated
Companies exploring international payment providers may consider Uniteller alongside other options based on their operational requirements.
Businesses should compare payment providers based on areas such as B2B payments, cross-border capabilities, Pay-in services, reporting, integrations, security, and scalability.
The right payment infrastructure should fit both current transaction needs and future expansion plans.
Conclusion
B2b cross border payments create several challenges for global companies, including currency management, settlement delays, reconciliation, security, compliance, and transaction visibility.
Modern payment solutions can help companies organize these processes more efficiently.
A strong business payment solution can provide better financial visibility while reducing manual work.
Companies can also combine online payment solutions, efficient Pay-in services, and secure cross border payments to create more structured global financial operations.
By improving international business payments, companies can strengthen supplier relationships and support long-term global growth.